Table of Contents
- Start With Property Condition Assessment
- Determine After-Repair Value Using Comparable Sales
- How to Estimate Repair Costs for a Flip
- Apply the 70% Rule to Set Maximum Allowable Offer
- Calculate Profit Using a House Flipping Profit Calculator
- Validate Local Market Demand and Resale Potential
- Evaluate Risk and Make Your Final Decision
- Frequently Asked Questions
Last Updated: October 13, 2026
Start With Property Condition Assessment
Understanding how to evaluate a property for a successful flip begins with knowing what you’re buying.
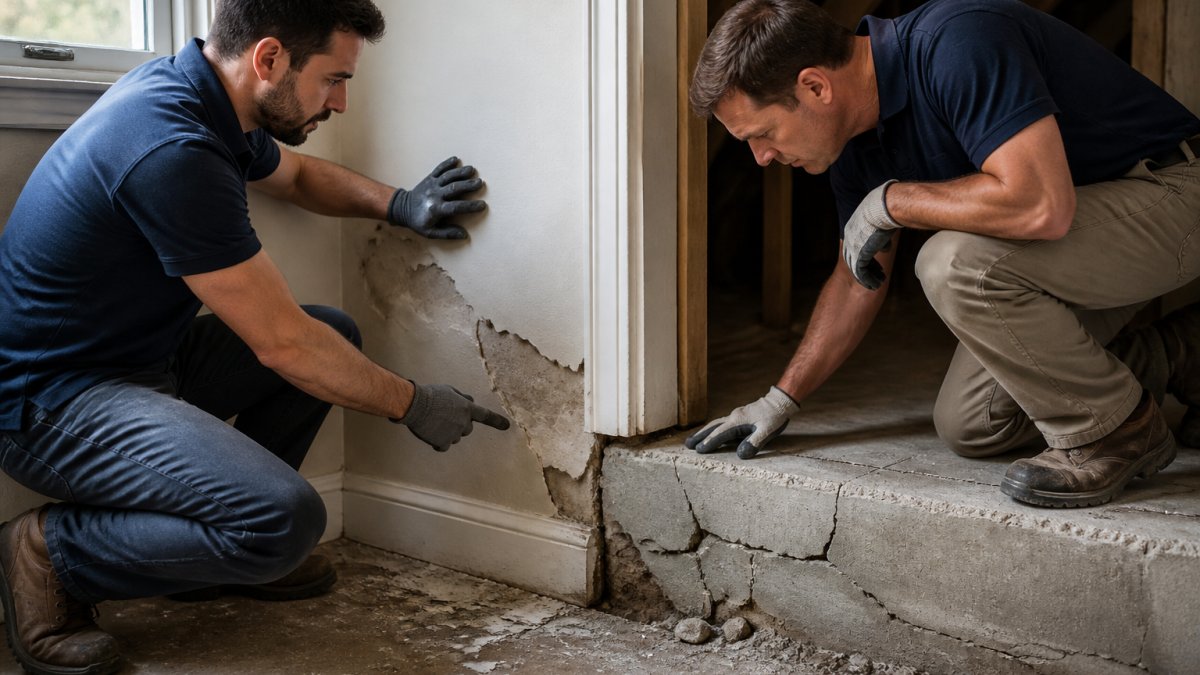
Document the roof, foundation, plumbing, electrical, and HVAC systems first, these are your biggest cost drivers, and foundation issues can kill a deal.
Cosmetic vs. Structural Issues
The difference between cosmetic and structural repairs determines your profit margin. Cosmetic repairs, paint, flooring, fixtures, finishes, are predictable, inexpensive, and fast. Structural repairs, foundation cracks, roof damage, plumbing problems, electrical code violations, load-bearing wall issues, are expensive, unpredictable, and can drag on for months. Buyers accept cosmetic work but not a property that fails inspection.
Using a House Flipping Due Diligence Checklist
Create a standardized checklist to evaluate every property consistently, preventing missed issues and enabling fair comparisons.
Your checklist should include:
- Foundation: Cracks, settling, water intrusion, moisture in basement
- Roof: Age, missing shingles, leaks, ventilation issues
- Exterior: Siding condition, windows, doors, gutters, grading
Document everything with photos and notes; this becomes your baseline for estimating repairs and justifying your offer to lenders.
Room-by-Room Inspection Checklist
A room-by-room walkthrough ensures you catch everything:
Exterior and Structure
- Foundation: Look for horizontal cracks wider than 1/4 inch, stair-step cracks in brick, or bowing walls, all signs of serious structural movement.
- Roof: Check for missing, curling, or broken shingles; rusted flashing; and sagging roof lines. If the roof is over 15 years old, budget for replacement.
- Siding and trim: Note rot, peeling paint, or gaps; wood siding often hides moisture damage.
Basement and Crawlspace
- Moisture: White chalky deposits (efflorescence), musty odors, or visible mold indicate chronic water intrusion.
- Structural supports: Sagging beams, cracked joists, or temporary jack posts are expensive to repair.
- Insulation and vapor barriers: Missing or damaged insulation increases energy costs and can lead to frozen pipes.
Living Areas
- Walls and ceilings: Cracks, water stains, or bubbling paint can signal plumbing leaks or foundation issues.
- Floors: Sloping, squeaks, or soft spots often indicate structural problems.
- Windows and doors: Sticking windows or doors can indicate foundation movement.
Kitchen and Bathrooms
- Plumbing: Run all faucets and flush toilets. Check under sinks for leaks and water damage. Look for slow drains.
- Cabinets and counters: Note water damage, delamination, or outdated finishes. These are cosmetic but add up.
- Ventilation: Ensure exhaust fans work and vent outside, not into the attic.
Electrical and HVAC
- Electrical panel: Identify the brand; some panels (like Federal Pacific or Zinsco) are known fire hazards and must be replaced.
- Wiring: Aluminum wiring (common in homes built 1965-1973) or knob-and-tube wiring both require expensive updates.
- HVAC: Systems older than 15 years are near the end of their life. Check for asbestos insulation on ductwork or pipes.
Permits and Code Compliance
- Pull permit history at the local building department; unpermitted additions, electrical work, or plumbing can delay resale or require costly retroactive permits.
- Check zoning regulations if you plan to add square footage or change the property’s use.
Bring a clipboard, flashlight, camera, and outlet tester to every showing. Take dated photos of every issue. These photos become your negotiation leverage and your repair estimate backup.
This approach turns a vague walkthrough into a repeatable, defensible evaluation.
Determine After-Repair Value Using Comparable Sales
After-repair value (ARV) is what the property will sell for after renovations, and it drives every other decision in your flip. It is not today’s value or your hoped-for price, it’s what similar, recently renovated properties in the same neighborhood actually sold for. Accurate assessment of these comparable sales ensures your budget remains realistic, though investors who choose to hold the asset instead of selling should also consider how to maximize rental income.
Finding Recently Sold Properties
Identify comparable sales within a half-mile radius, in the last 90 days, with similar square footage, lot size, and post-renovation condition.
Use these resources:
- MLS (Multiple Listing Service): Your local MLS is the most reliable source. Work with a real estate agent who has access to detailed sold data.
- Public records: County assessor websites show sale prices and property details.
- Online platforms: Zillow, Redfin, and Realtor.com provide sold listings, though details vary.
Pull at least 5-10 comps for any property you’re serious about; more data means a more confident ARV estimate.
Adjusting Comps for Market Conditions
Comparable properties are rarely identical, so adjust for differences: a six-month-old sale in a rising market may not reflect today’s value, and a property in a better neighborhood needs a downward adjustment.
Common adjustments include:
- Time adjustment: If the market is appreciating, adjust older sales upward. If it’s declining, adjust downward.
- Location adjustment: A property on a main street is worth less than an identical home on a quiet street.
- Condition adjustment: A fully renovated comp is worth more than one needing work.
Make conservative adjustments; if unsure whether a comp is truly comparable, find another. Overestimating ARV is the fastest way to overpay.
How to Estimate Repair Costs for a Flip
Repair costs are your second-largest variable after purchase price. Get detailed estimates from licensed contractors rather than your gut or online calculators, they have real-world pricing data for permits, labor, and materials in your market.
Scope of Work and Contractor Estimates
Define exactly what you’re repairing before getting estimates. A vague scope produces vague bids, contractors will either bid high to cover uncertainty or bid low and change-order you to death.
Your scope should specify:
- What surfaces or systems are being repaired or replaced
- Materials being used (brand, grade, type)
- Labor expectations (timeline, crew size)
Get at least three competitive bids for major work and compare price, timeline, and warranty. A contractor who finishes in four weeks beats one who takes eight, because your carrying costs are lower.
Building in Contingency Reserve
Surprises happen on every flip, mold behind a wall, an undersized electrical panel, asbestos requiring abatement. Build a contingency reserve of 10-20% of your total repair estimate and assume problems will be found.
Apply the 70% Rule to Set Maximum Allowable Offer
The 70% rule is a quick filter for potentially profitable deals: multiply the after-repair value by 0.70, then subtract total repair costs to get your maximum purchase price.
Formula: (ARV × 0.70) − Repair Costs = Maximum Allowable Offer
This leaves 30% of ARV for carrying, financing, and selling costs plus profit. In competitive markets, adjust down to 65% or even 60%.
Calculate Profit Using a House Flipping Profit Calculator
Your actual profit depends on every deal cost. Most new flippers forget carrying and selling costs, which can consume 15-25% of ARV.
Accounting for All Carrying Costs
Carrying costs are expenses you pay while you own the property:
- Mortgage interest: If you’re financing the purchase and renovation
- Property taxes: Monthly or quarterly payments
- Insurance: Homeowners insurance on the property
These add up quickly: a six-month flip at 6% interest on a $300,000 loan costs roughly $9,000 in interest alone, and with taxes, insurance, and utilities, a typical project sees $15,000-$20,000 in carrying costs.
Full Deal-Cost Worksheet
To calculate true net profit, account for every dollar in and out:
Acquisition Costs
- Purchase price
- Closing costs (title, escrow, recording fees): typically 2-5% of purchase price
- Loan origination fees and points
Renovation Costs
- Contractor labor and materials
- Permits and fees
- Dumpster rental and cleanup
Carrying Costs
- Mortgage interest
- Property taxes
- Insurance
Selling Costs
- Real estate agent commission: typically 5-6% of sale price
- Seller closing costs (title insurance, transfer taxes, escrow fees): typically 1-3% of sale price
- Staging and photography
Taxes
- Capital gains tax (short-term, based on your income bracket)
- Depreciation recapture (if applicable)
Net Profit Formula
Net Profit = ARV − (Purchase Price + Acquisition Costs + Renovation Costs + Carrying Costs + Selling Costs + Taxes)
Computing Net Profit and ROI
Return on investment (ROI) measures profit relative to cash invested, put down $50,000 and make $30,000, and your ROI is 60%. Most flippers target 15-25% net profit margins on cash invested.
Sensitivity Analysis and Downside Scenarios
A single-point profit estimate is fragile. Smart investors run sensitivity analysis against three common downside scenarios:
Scenario 1: ARV Falls 10%
If the market softens and your ARV drops from $400,000 to $360,000, your profit shrinks by $40,000. If your original profit was $50,000, it’s now $10,000, an 80% reduction.
Scenario 2: Repairs Exceed Budget by 20%
If your repair budget was $50,000 and overruns push it to $60,000, that extra $10,000 comes directly out of profit.
Scenario 3: Project Takes 3 Months Longer
Carrying costs for an extra three months on a $300,000 loan at 6% add roughly $4,500 in interest, plus property taxes, insurance, and utilities.
Run your numbers with conservative assumptions: ARV 5-10% below your best estimate, repairs 10-20% above budget, and timeline 2-3 months longer than planned. If the deal still works, it’s robust. If it doesn’t, you need a lower purchase price or a different property.
Worked Example with Transparent Assumptions
Here is a sample deal showing how these numbers come together.
Property Details
- Purchase price: $250,000
- ARV: $400,000
- Repair budget: $50,000
Acquisition Costs
- Closing costs (3%): $7,500
- Loan origination (2%): $5,000
- Inspection/appraisal: $1,000
Carrying Costs (6 months)
- Mortgage interest (6% on $250,000): $7,500
- Property taxes: $3,000
- Insurance: $1,200
Selling Costs
- Agent commission (6%): $24,000
- Seller closing costs (2%): $8,000
- Staging: $2,000
Total Costs
- Purchase price: $250,000
- Acquisition: $13,500
- Renovation: $57,500
Net Profit
- ARV: $400,000
- Total costs: $368,500
- Net profit: $31,500
This deal is profitable, but the margin is thin: a 10% ARV drop or 20% repair overrun would wipe out most of the profit.
Always run at least three scenarios, base case, pessimistic, and worst case, before making an offer. If the worst case still yields a positive return, you have a margin of safety. If not, negotiate harder or walk away.
Validate Local Market Demand and Resale Potential
ARV estimates are only as good as the market’s actual demand, a declining neighborhood pulls down your exit price no matter how well you renovate. Research the local market before committing capital: are homes selling quickly or sitting, are prices rising or declining, and who is buying? Talk to local agents who know which neighborhoods are hot.
Evaluate Risk and Make Your Final Decision
Every flip carries risk. Evaluate it honestly and decide whether the potential profit justifies it.
When to Walk Away
Walk away if:
- The numbers don’t work. If the deal doesn’t meet your minimum profit threshold, pass.
- Structural issues are severe. Major foundation problems, roof replacement, or electrical rewiring dramatically increase costs and timelines.
- The market is weak. Slow comparable sales or declining prices make your exit harder.
The best deal you’ll ever pass on is one that would have failed. Discipline separates successful flippers from those who lose money.
When you do find a deal that works, solid numbers, manageable risk, strong market demand, you need reliable financing to move forward. Real Estate Investment loans and Bridge Loans are designed specifically for fix-and-flip investors who need fast capital and flexible terms.
Learning how to evaluate a property for a successful flip requires discipline across multiple dimensions: honest assessment of condition, accurate ARV research, detailed cost estimation, and realistic market analysis. Investors who consistently profit follow a systematic process and stick to their criteria.
Frequently Asked Questions
What is the 70% rule in house flipping?
The 70% rule is a straightforward formula: Maximum Allowable Offer = (After-Repair Value × 0.70) − Repair Costs. It ensures your purchase price leaves room for carrying costs, selling costs, and profit. For example, if a property’s ARV is $300,000 and repairs cost $50,000, your maximum offer should be around $160,000. This rule protects you from overpaying and keeps deals profitable when market conditions shift.
How do you calculate after-repair value for a flip?
After-repair value (ARV) is determined by analyzing recently sold comparable properties in the same neighborhood. Find 3-5 homes that sold within the last 90 days with similar square footage, condition, and features. Adjust their sale prices up or down based on differences (extra bedrooms, updated kitchen, lot size). Average the adjusted prices to estimate what your property will sell for after renovation. This comparison approach is more reliable than online estimates alone.
What costs should I include when analyzing a flip property?
Include purchase price, all repair and renovation costs, holding costs (property taxes, insurance, utilities), financing costs (interest, origination fees), closing costs on purchase and sale, contractor labor, permits, and a contingency reserve of 10-15% of repair costs. Many investors underestimate carrying costs, property taxes and interest can add significantly to monthly expenses depending on location and loan terms. A complete cost worksheet prevents surprise losses at the end.
How do I know if a property is a good flip or better as a rental?
Compare cash flow potential. If the property’s monthly rental income minus expenses (mortgage, taxes, insurance, maintenance) exceeds 1% of your total investment, it may work better as a rental. If repair costs are high, the neighborhood appreciates slowly, or buyer demand is weak, rental cash flow often outperforms a quick flip. Evaluate both scenarios using your profit calculator before committing to either strategy.