Quick Summary
Lenders assess collateral valuation by estimating what the property would sell for and how much debt it can safely carry. Most use a full appraisal, a broker price opinion, an automated valuation model, or an income approach for rental property. Lenders then apply haircuts and subtract existing liens to determine your usable proceeds.
- Gather your purchase contract, mortgage statements, tax bills, and property photos before applying.
- Ask which valuation method your lender uses and who orders it, and whether you pay the cost at closing.
- Clarify whether the lender uses as-is value or after-repair value, since this can change your loan amount.
- Subtract every senior lien, closing costs, and reserves from the lender’s underwritten value to estimate usable proceeds.
- If the valuation comes in low, review the report, submit additional evidence, or adjust your loan request.
Table of Contents
- How Lenders Value Collateral for a Bridge Loan
- Step 1: Gather the Documents Needed for a Bridge Loan
- Step 2: Order the Bridge Loan Appraisal Process
- Step 3: Establish the As-Is Property Value for Bridge Loans
- Step 4: Calculate Loan-to-Value and Available Equity
- How Long Bridge Loan Collateral Valuation Takes and What Can Delay It
- Responding to a Valuation That Comes In Low
- Your Next Step: Prepare Your Property File Before You Apply
- Frequently Asked Questions
How Lenders Value Collateral for a Bridge Loan
Last Updated: October 31, 2026
Bridge loans move fast, and the property behind them decides how far and how fast they can go, which is why a clear understanding of collateral valuation matters from the very start. Lenders typically review collateral by asking what the property would sell for and how much debt it can safely carry. Understanding that question helps you prepare a stronger file before you apply. (Source: guidance on preparing a loan application packet)
A bridge loan is short-term financing secured by real estate. Lenders often use the property’s value to help set the loan amount, so the valuation process is a core part of underwriting.
Borrowers who understand this process tend to ask better questions and avoid avoidable delays. The sections below walk through each stage, from document collection to a low-valuation response.
Step 1: Gather the Documents Needed for a Bridge Loan
Start by collecting the paperwork lenders will request. A complete file lets the valuation begin sooner and reduces back-and-forth.
Typical documents include: (Create a loan application packet)
- Property address and legal description
- Purchase contract or current deed information
- Current mortgage statements showing any outstanding balance
- Recent property tax bills
- Property photos showing current condition
- Scope of work and renovation budget, if the project involves repairs
- Proof of funds for your down payment and closing costs
- Entity documents, such as an LLC operating agreement, if you borrow through a company
Gather these before you apply. Missing documents are one of the most common causes of delay in the bridge loan process.
Step 2: Order the Bridge Loan Appraisal Process
Once the lender agrees to move forward, it selects a valuation method. This is the decision most borrowers overlook, and it is where the process diverges from a conventional mortgage. Bridge lenders may use different valuation methods depending on the loan and property. To see the full application flow and what lenders evaluate beyond the valuation, read the bridge loan application process step by step.
Common valuation methods include:
- Full appraisal. A state-licensed or state-certified appraiser inspects the property, measures it, analyzes comparable sales, and delivers a written opinion of value, typically on the Uniform Residential Appraisal Report (Form 1004) for single-family homes or Form 1025 for small multifamily. This is the most defensible and the slowest option.
- Broker price opinion (BPO). A real estate broker provides an opinion of value based on an exterior inspection and comparable sales. It is faster and less expensive than an appraisal but carries less weight and is more vulnerable to challenge.
- Automated valuation model (AVM). A data-driven estimate drawn from public records and recent sales.
- Income approach. For rental and commercial property, the lender may weight net operating income and a market capitalization rate alongside sales comparables. A property that cash-flows well can support a higher value than its comparable sales alone suggest.
Ask the lender which method it will use, who orders it, and whether the cost is passed to you at closing.
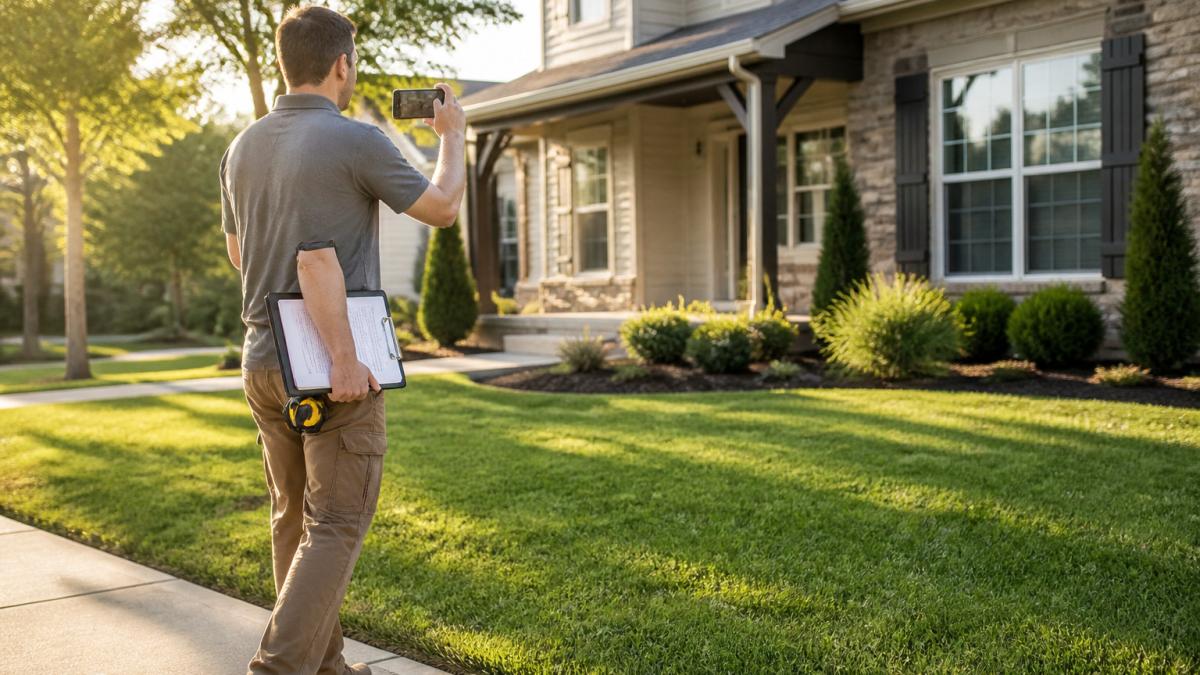
Expect the appraiser or broker to:
- Inspect the interior and exterior of the property
- Measure the living area and note the property’s condition
- Compare the property to recent sales of similar homes nearby
- Record the findings in a formal report
Ask your lender whether it will accept a recent appraisal you already hold.
Confirm the valuation method and who orders it before you commit to any fees.
Step 3: Establish the As-Is Property Value for Bridge Loans
Many bridge lenders focus on the as-is value, which is what the property is worth in its current condition. This can matter for fix-and-flip projects, where the after-repair value may be higher than today’s price.
Clarify early whether your lender uses as-is value, after-repair value, or both. This single detail can change your loan amount significantly.
Step 4: Calculate Loan-to-Value and Available Equity
Lenders measure risk with the loan-to-value ratio (LTV), but the number that matters is not the one on your purchase contract. It is the value the lender is willing to underwrite after adjustments and existing debt. The basic formula is simple:
LTV = Loan Amount ÷ Property Value × 100
For example, a property valued at $400,000 with a $280,000 loan has an LTV of 70 percent. Lenders typically set maximum LTV limits, which vary by property type and borrower profile.
Equity matters too, but the usable figure is smaller than most borrowers expect. Work through it in three steps.
Step one: start with the lender’s value, not the market value. Lenders apply haircuts for condition, vacancy, renovation needs, and marketability. A property that needs a full kitchen and two bathrooms may be underwritten below its as-is appraised value because the lender assumes a buyer would discount it for the work. Ask what adjustments the lender applied.
Step two: subtract every senior lien, not just the first mortgage. Add up the first mortgage, any second mortgage or home equity line, tax liens, mechanic’s liens, and judgments that attach to the property. These all sit ahead of your new loan. Ensuring that the underlying collateral remains unencumbered by these hidden obligations is as vital as preparing for property appraisals to confirm that the asset value supports the total debt stack.
Step three: subtract closing costs and required reserves. The lender will hold back loan fees, title and escrow charges, and often several months of interest or taxes. Those amounts reduce the cash you can actually draw.
A worked example:
- Appraised value: $400,000
- Lender haircut for condition and vacancy: $20,000
- Underwritten value: $380,000
- Maximum LTV at 70 percent: $266,000
- Existing first mortgage: $150,000
- Existing second lien: $25,000
- Closing costs and reserves: $12,000
- Usable proceeds: $79,000
That is a very different number from the $250,000 of raw equity the simple subtraction suggests. Lenders review this math closely, so accurate figures on every lien and your current loan balance help avoid surprises at the closing table.
Do not assume the lender will advance the full maximum LTV. Many bridge lenders apply an advance rate to the underwritten value and then cap the total debt against the property, including existing liens. Confirm both the LTV limit and the advance rate before you size your request.
Run this math before you apply. The DSCR calculation guide for rental property walks through the formula, NOI, and lender requirements step by step. If the usable proceeds fall short of your project budget, you have time to adjust the loan request, bring more cash, or renegotiate the purchase price rather than discovering the gap during underwriting.
The worked example below shows how the usable proceeds come out far lower than the raw equity figure suggests.
| Item | Value | Note |
|---|---|---|
| Appraised value | $400,000 | Starting point before adjustments |
| Lender haircut | $20,000 | Condition and vacancy adjustment |
| Underwritten value | $380,000 | Value the lender actually underwrites |
| Maximum LTV at 70% | $266,000 | Cap on total debt against the property |
| Existing first mortgage | $150,000 | Senior lien ahead of the new loan |
| Existing second lien | $25,000 | Also sits ahead of the new loan |
| Closing costs and reserves | $12,000 | Held back from cash drawn |
| Usable proceeds | $79,000 | Cash actually available to draw |
How Long Bridge Loan Collateral Valuation Takes and What Can Delay It
Timelines vary by lender, property location, and appraiser availability. Some valuations are completed within days, while others take several weeks. Delays often come from:
- Incomplete borrower documents
- Difficulty scheduling property access
- Limited comparable sales in the area
- Title issues or unresolved liens
- Property condition problems that require extra review
Ask your lender for an expected timeline at the start, and respond to requests quickly. Fast responses keep the process moving.
Responding to a Valuation That Comes In Low
A low valuation can feel discouraging, but it is not always the final answer. You have several options:
- Review the appraisal report. Check the comparable sales the appraiser used and confirm the property details are accurate.
- Submit additional information. Provide recent improvements, permits, or updated photos if they affect value.
- Request a reconsideration of value. Explain specific errors or missing comparables with supporting evidence.
- Adjust the loan request. Consider a smaller loan or a larger down payment to fit the approved value.
Watch out: Do not assume a low valuation means the deal is dead. Review the report carefully before deciding your next move. If credit or equity is weaker than expected, see how to qualify for commercial bridge loans with bad credit.
Your Next Step: Prepare Your Property File Before You Apply
Before you submit an application, assemble your documents, confirm your current mortgage balance, and ask your lender how they value collateral. A well-prepared file shortens the valuation timeline and gives you more control over the outcome.
Asset Point Capital provides nationwide real estate financing. Reach out to discuss your property and timeline.
Frequently Asked Questions
How much equity is needed for a bridge loan?
Equity requirements depend on the lender and the deal structure. Asset Point Capital’s program pages and a quote from the team give the current terms for your property type and loan purpose. In general, lenders measure equity by subtracting every outstanding mortgage and lien from the property’s value, then compare the remaining amount to the loan request. Gather your current payoff statements and a recent value estimate before you apply so you can run this math yourself.
Do I need an appraisal for a bridge loan?
Most bridge lenders order a formal appraisal or a comparable valuation before funding, because the collateral is what secures the loan. Some lenders accept a broker price opinion or an internal valuation for smaller or lower-risk deals. Ask the lender which method it uses and what it requires from you, since that choice affects how long the valuation takes and how much detail you need to provide.
How long does bridge loan collateral valuation take?
Timelines vary with the valuation method, property access, and how quickly the required documents reach the lender. Ordering the valuation as soon as the term sheet is issued, and making the property available for inspection on short notice, usually keeps the process moving. Ask Asset Point Capital for its current timeline for your property type, and confirm which steps depend on you.
What happens if the lender’s valuation is lower than expected?
A lower valuation reduces the loan amount the lender will advance, which can leave a gap in your purchase or renovation budget. Review the valuation report for errors in comparable sales, property condition, or square footage. If you find a factual error, submit the correction with supporting evidence. Then decide whether to cover the gap with additional equity, adjust the scope of the project, or renegotiate the purchase price before you commit.
